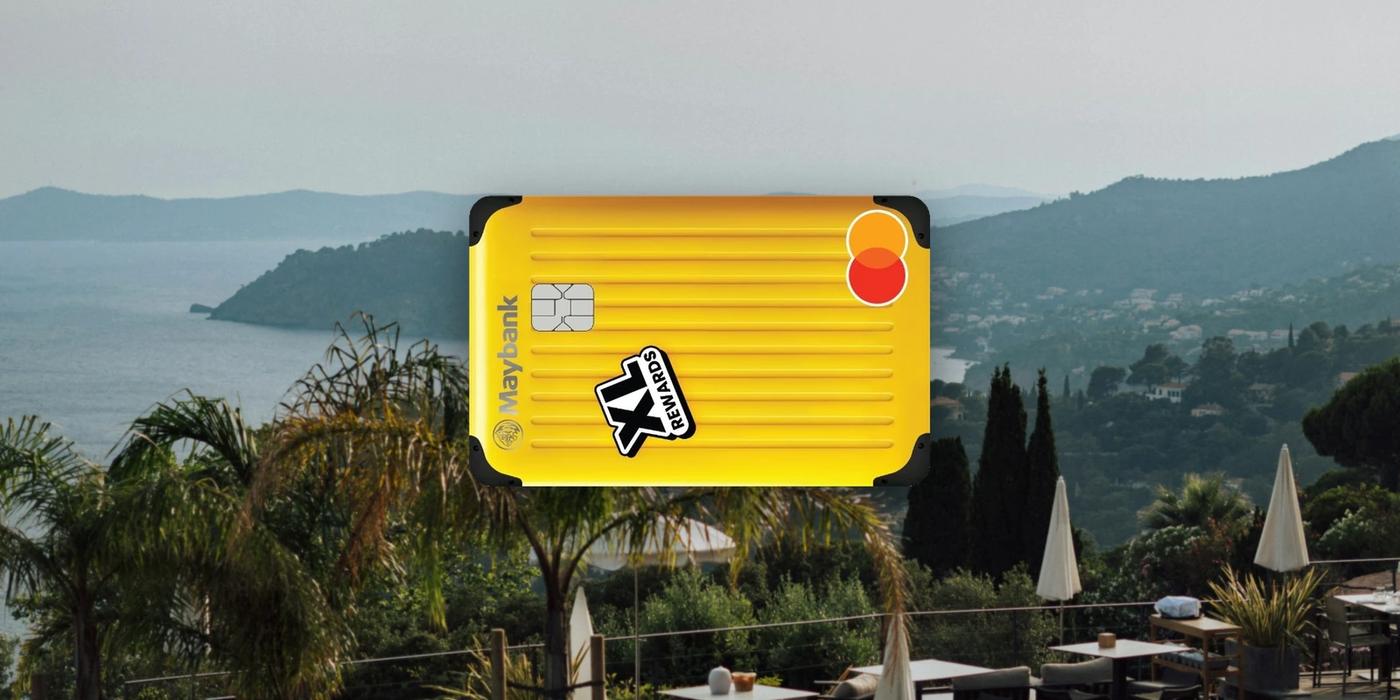
The best foreign-currency card here, if you are under 40 and spend every month.
| Eligibility | Min income | Base earn | Bonus earn |
|---|---|---|---|
| Aged 21 to 39at application, no exceptions | S$30,000S$45,000 for foreigners | 0.4 mpdand what a quiet month pays | 4 mpdall FCY, dining, shopping, travel |
| Monthly cap | Activation floor | Annual fee | Points expiry |
| S$1,000shared across all bonus categories | S$500total spend, or everything drops to base | S$87.20waived two years, then on S$6,000 spend | 12 to 15 monthsshort, unless on Rewards Infinite |
Maybank spent years being the bank nobody in the miles conversation mentioned, and then quietly built one of the most competitive foreign currency cards in Singapore. The XL Rewards card is what happens when a challenger stops copying and starts undercutting.
4 mpd on every foreign currency transaction, with no online-or-contactless condition attached, which is unusually clean in a market that loves attaching one. Dining, shopping, travel and entertainment and also travel agencies are on the bonus list rather than quietly excluded like almost everywhere else.
This sounds like a dream too good to be true. But like all cards, there’s a catch. For the XL Rewards, there’s a minimum spend of S$500 in the month for the bonus to exist. Also it’s the 12-15 month expiry terms means you need to be on your toes to redeem your miles every year and ensure that you’re hitting the conversion blocks of 25,000 TREATS (10,000 miles).
Btw they also decided that this card is only available for those Aged 21 to 39 years old.
Annual Fee
S$87.20, waived for the first two years, then waived again on S$6,000 of annual spend.
| Card | First year | Second year on |
|---|---|---|
| Principal card | Waived | S$87.20 |
| Supplementary card | Waived | Free |
The cheapest card in this series by a distance, and the waiver condition lines up exactly with the spending you have to do anyway to earn anything. If you are clearing the S$500 monthly floor, the fee takes care of itself.
Welcome Bonus
There is no sign-up bonus. Maybank pays S$10 cashback on your first spend, and that is the whole of it.
Most cards in this lineup open with somewhere between 20,000 and 38,000 miles. This one opens with ten dollars. If a sign-up bonus is what you are here for, apply for a Maybank card that has one first: Horizon and World Mastercard both carry a Samsonite welcome gift. The welcome offer is a new-to-bank offer, so taking XL Rewards first spends your one shot at it.
New cardholders do get one thing, and it is not miles. Approved between 1 July and 30 September 2026, the 4 mpd monthly cap rises from S$1,000 to S$1,500 for your approval month plus the three that follow, which is 6,000 miles a month instead of 4,000. Worth having, but read it for what it is: a bigger cap, not free miles. You still have to spend the extra S$500 every month to see any of it, and the offer closes on 30 September 2026.
The bigger cap is for cardholders new to the XL Rewards Card, and Maybank excludes anyone who cancelled one in the nine months before approval. Check the current terms with Maybank before you count on it.
How many miles do I earn?
4 miles per dollar on all foreign currency and four broad SGD categories, capped at S$1,000 a month in total.
| Spend type | Rate | Condition | Cap |
|---|---|---|---|
| All foreign currency | 4.0 mpd | Any channel | Shared S$1,000 |
| Dining, shopping, travel, entertainment | 4.0 mpd | Any channel | Shared S$1,000 |
| Everything else | 0.4 mpd | Uncapped | |
| Any category in a month under S$500 | 0.4 mpd | Floor was missed | Uncapped |
No channel rules is the quiet advantage. Nearly every 4 mpd card here makes you satisfy a category and a payment method at once. This one does not care whether you tapped, inserted or typed the number in, which on foreign currency removes the most common way people lose a bonus without realising.
The cap is shared, not per category, so S$1,000 is the total across FCY, dining, shopping, travel and entertainment combined.
What spend actually counts for the bonus?
All foreign currency, plus dining, shopping, travel and entertainment in SGD. Supermarkets are the notable absence.
| What you’re buying | Bonus? | key points |
|---|---|---|
| 🌏 Anything in foreign currency | ✓ Yes | Online or contactless both works |
| 🧳 Travel agencies and OTAs | ✓ Yes | MCC 4722 is on the list, which is rare |
| 🍜 Dining and food delivery | ✓ Yes | Restaurants, fast food and caterers |
| 🛍 Retail and department stores | ✓ Yes | A wide list of shopping MCCs |
| 🎬 Cinemas, bars, ticketing | ✓ Yes | Entertainment is a named category |
| 🏪 Supermarkets | ✕ No | MCC 5411 is absent from the bonus list entirely |
| 💡 Utilities, insurance, education | ✕ No | Excluded outright, as on most cards |
The Catch 1: Min Spend
S$1,000 cap with a S$500 floor underneath it.
This card has a ceiling and a floor, and the floor is the one that catches people.
| Total card spend that month | Rate on bonus categories | Miles on S$800 |
|---|---|---|
| S$499 | 0.4 mpd | 320 |
| S$500 or more | 4.0 mpd | 3,200 |
The floor counts total card spend, bonus and non-bonus together, so it is easier to clear than it first reads. It is still the opposite failure mode to a cap: a cap costs you the spend above it, a floor costs you everything below it.
If your spend is irregular, this might be a serious catch you need to take into account before applying.
Catch 2: The Expiry Trap
12 to 15 months expiry means you need to be on your toes
Most miles cards give you two years or more. This one gives you 12 to 15 months from earning, and it is the single most expensive detail on the card. TREATS Points expire one year from the quarterly period in which they were earned.
| Points Earned | Expire On |
|---|---|
| 1 Jan – 31 Mar 2026 | 31 Mar 2027 |
| 1 Apr – 30 Jun 2026 | 30 Jun 2027 |
| 1 Jul – 30 Sep 2026 | 30 Sep 2027 |
| 1 Oct – 31 Dec 2026 | 31 Dec 2027 |
You need 25,000 TREATS to transfer anything at all, which is 10,000 miles, which is S$2,500 of spend in a bonus category. It means you really need to do some regular check-ins to fit your miles within the blocks.
| Bonus spend a month | Total card spend | TREATS a month | Months to reach 25,000 |
|---|---|---|---|
| S$1,000, the full cap | S$1,000 or more | 10,000 | 2.5 |
| S$500 | S$500 or more | 5,000 | 5 |
What I do about it. A calendar reminder, once a year, to check the balance and move whatever is transferable. It is the least interesting piece of admin in miles and the one with the highest return, because the alternative is watching a year of spending quietly evaporate.
The permanent fix is Rewards Infinite, which removes the expiry entirely while you are enrolled. But to qualify for this program, you need to spend S$24,000 in a year, which means S$2,000/mth. This puts you way past the S$1,000 monthly bonus cap, and is not optimal.
That is unless you’re investing into the Maybank ecosystem because this amount pools from all your cards.
Transfer Partners
25,000 TREATS to 10,000 miles, at S$27.25 a conversion.
| Programme | TREATS for 10,000 miles |
|---|---|
 Singapore Airlines KrisFlyer | 25,000 |
 Cathay Asia Miles | 25,000 |
Two things soften that. Maybank World Mastercard holders get the transfer fee waived, and enrolling in Rewards Infinite removes the expiry entirely. This card rewards being inside the Maybank ecosystem more than most, which is presumably the whole idea.
Before any redemption, always check the route you want is actually available. The worst thing you can do is diversify into another mileage program with no redemption in mind.
What should I pair it with?
Here is what happens when you blow through S$1,500 of qualifying spend in one month, past the $1,000 bonus cap.
| Spend | Rate | Miles |
|---|---|---|
| First S$1,000 | 4.0 mpd | 4,000 |
| Next S$500 | 0.4 mpd | 200 |
| Total | 2.8 mpd effective | 4,200 |
Move that S$500 to a second 4 mpd card and it pays 2,000 instead of 200. That one move beats every other optimisation in this article combined and takes about zero effort.
Pick the card that covers this one’s gaps: the spend it refuses to pay on.
Groceries are the one people forget. Supermarkets are not on the eligible list at all, so a S$600 monthly shop earns 240 miles here instead of 2,400. For most households, it is the single biggest hole in the month.
| The gap | What it costs you | What closes it |
|---|---|---|
| Groceries | 0.4 mpd on a bill almost everyone has | UOB Preferred Visa, UOB Ladies (Family) |
| Spend past the shared S$1,000 cap | 0.4 mpd instead of 4 | UOB Visa Signature, HSBC Revolution |
Build your miles card stack
One card never covers everything. Put in what you actually spend and see which cards to hold together, and what to put on each.
Build my stack→The verdict, restated
If you are under 40 and spend regularly in the bonus categories over S$500 per month. This is the most straightforward 4 mpd card . Two things worth knowing on day one: a month under S$500 earns 0.4 mpd on everything, and the points expire quickly.
Sources
Maybank XL Rewards Card TREATS Points Programme T&Cs, checked 27 July 2026, and the Maybank XL product page. Rates, fees and caps correct as of 5 August 2026. A promotional S$1,500 monthly cap for new cardholders was reported as running to 30 September 2026; the standing S$1,000 cap is used here because promotional caps decay. The foreigner minimum income was not confirmed on an official page. This guide shares my own experience for education, it is not financial advice, and card terms change: always verify with the bank before applying.