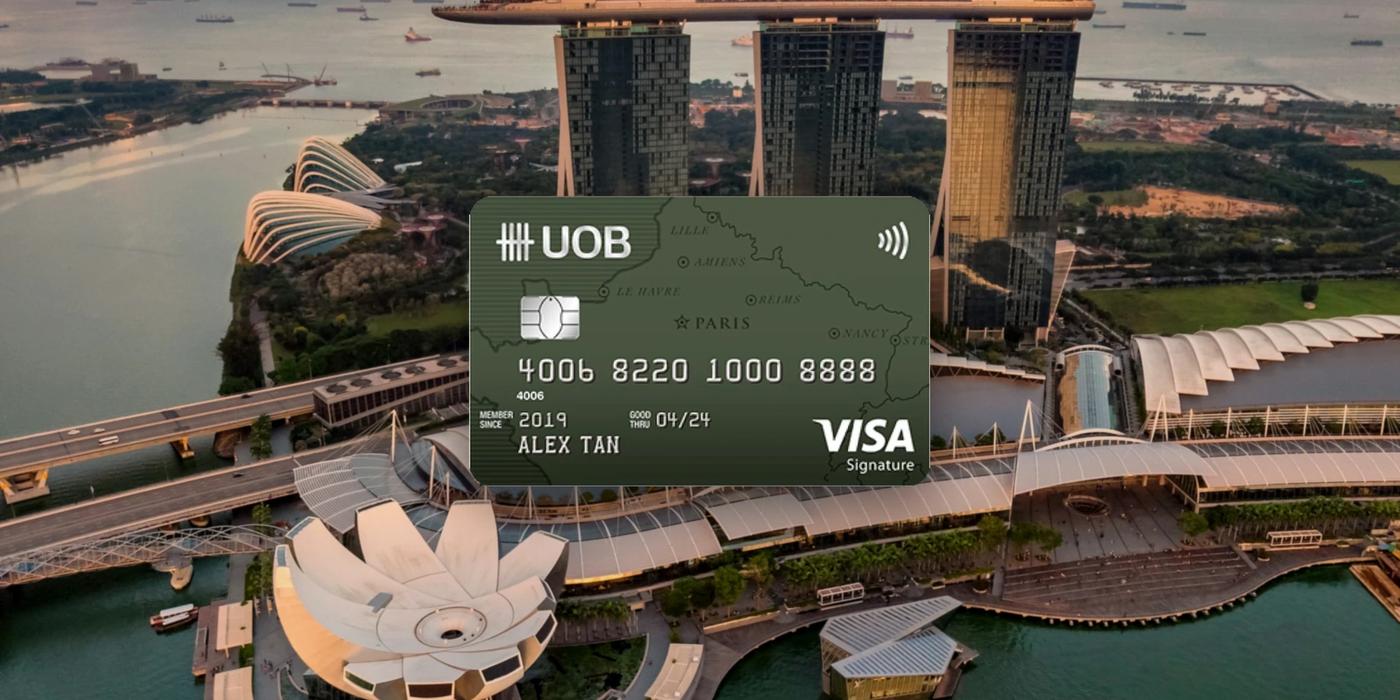
Superb if you clear S$1,000 in one category every month, close to pointless if you miss it
| Min income | Base earn | Bonus earn | Minimum spend |
|---|---|---|---|
| S$30,000S$40,000 for foreigners | 0.4 mpdand what a missed minimum pays | 4 mpdoverseas, or contactless and petrol | S$1,000per category, per statement month |
| Monthly cap | Annual fee | Points expiry | Transfer blocks |
| S$1,200per category, so S$2,400 total | S$218first year waived | 2 yearsfrom the end of the earning quarter | 10,000 miles5,000 UNI$, S$27 a time |
Most Singapore miles cards are designed for people who spend a bit. UOB went the other way with the Visa Signature and built one for people who spend a lot, then made very sure the casual user gets nothing out of it.
The headroom is genuinely the best here. Two separate 4 mpd buckets, one for overseas and foreign currency, one for contactless and petrol, each capped at S$1,200, so S$2,400 of bonus spend a month at a fee you can usually get waived. Nothing else at this price comes close.
The catch is a S$1,000 minimum in each bucket, every statement month, before either pays anything above base. Not a reduced rate. Base. That single condition is what makes this either the best card in your wallet or the most pointless one.
Annual Fee
S$218, waived the first year, and usually waived after that on regular use.
| Card | First year | Second year on |
|---|---|---|
| Principal card | Waived | S$218 |
| Supplementary card | Waived | Free |
The part people miss: UOB charges their annual fee in points.
- UNI$ 6,500 for full waiver
- UNI$ 3,250 + S$109 for half waiver
And UOB automatically deducts them to waive your annual fees. This could be a really sad situation if you missed out applying for an annual fee waiver, as 6,500 UNI$ is worth roughly 13,000 miles. That is months of hard-earned miles disappearing.
So do check your Rewards+ Tab for any deductions and apply for waiver accordingly.
UOB is among the more reliable banks for a waiver on regular use, so in practice this sits closer to a free card than the sticker suggests. It still asks you to make a phone call once a year, which a card with no annual fee does not.
Welcome Bonus

UOB Visa Signature
Welcome bonus
- S$100 Samsung e-voucher
Offer ends 2026-09-30
Welcome bonus
- S$90 Cash via PayNow
The same promotion runs flash tiers worth more, including Cash via PayNow at S$200 and Samsonite Straren Spinner 67/24 at S$600, but those go to the first few applicants at a set time each day. Nearly everyone receives the reward above.
Offer ends 2026-09-30
Sign-up rewards change often, so confirm the current offer before you apply. New customers only, meaning no card from UOB in about the last 12 months.
Sign-up offers move monthly and almost always carry a "new to bank" condition, meaning no UOB card in the past 12 months.
How many miles do I earn?
4 miles per dollar in either bucket, but only once that bucket clears S$1,000 in the statement month.
| Bucket | Rate | Minimum | Cap |
|---|---|---|---|
| Overseas and foreign currency | 4.0 mpd | S$1,000 | S$1,200 / month |
| Contactless and petrol | 4.0 mpd | S$1,000 | S$1,200 / month |
| Everything else, or a missed minimum | 0.4 mpd | none | Uncapped |
The two buckets are independent. Clearing one does nothing for the other, so a month where you spend S$900 in each earns base on all S$1,800 of it. That is the failure mode to design around, and it catches more people than the cap ever will.
Where the Bonus Disappears
This is the section that matters on this card. There is no clever routing to talk about, because UOB shut those doors years ago. What there is instead is a line at S$1,000 that quietly turns 4 mpd into 0.4.
| Contactless spend in the period | Rate | Miles |
|---|---|---|
| S$999 | 0.4 mpd | 400 |
| S$1,000 | 4.0 mpd | 4,000 |
One dollar is worth 3,600 miles at that threshold. Not a loophole, just reading the terms. If you are close to the line late in the period, deliberately topping up is worth more than any other optimisation on this card, and it is the only real play it has.
| The trap | Bonus? | What actually happens |
|---|---|---|
| 📅 Statement month, not calendar month | ✕ No | The month you are budgeting is not the one UOB counts. Check your statement date |
| ➗ Splitting spend across both buckets | ✕ No | They are independent. S$900 in each earns base on all of it |
| ⛽ Filling up at SPC or Shell | ✕ No | Both excluded from the petrol bonus, though petrol otherwise counts |
| 📱 Paying by phone | ✓ Yes | Apple Pay, Google Pay, Samsung Pay and UOB Mighty all count |
| 💳 Tapping the physical card | ✓ Yes | Visa payWave qualifies here, unlike on the Preferred Visa |
Atome earns no bonus UNI$ on UOB cards, and Amaze has been blocked on every UOB card since 2024. If you have read about either route working, it was not on this one.
Transfer Partners
UNI$ pool across every UOB card you hold, which is genuinely useful if you carry more than one: a stranded balance on one card can be topped up by another. Transfers move in blocks of 5,000 UNI$, which is 10,000 miles, at S$27 a time.
| Programme | UNI$ for 10,000 miles |
|---|---|
 Singapore Airlines KrisFlyer | 5,000 |
 Cathay Asia Miles | 5,000 |
The tighter constraint is expiry: 2 years from the end of the earning quarter. That sounds generous until you have a couple of quiet months and a balance that never reaches a transfer block.
Before any redemption, always check the route you want is actually available. The worst thing you can do is diversify into another mileage program with no redemption in mind.
What should I pair it with?
Worth being honest about the shape of this card: the cap is rarely the problem. The minimum is. Most people who hold this card lose miles at the bottom of the range, not the top. If you are regularly hitting S$1,200 in a bucket, this is doing exactly what it was built to do.
Something with no minimum, so a quiet month still earns something.
The gap on this card is not a category, it is a condition. What it needs alongside it is a card that pays on whatever you spend, however little of it there is.
| The gap | What it costs you | What closes it |
|---|---|---|
| A month under S$1,000 in a bucket | The entire bonus, not part of it | HSBC Revolution, Citi Rewards |
| Online shopping | 0.4 mpd, since online is not contactless | Citi Rewards, UOB Preferred Visa |
| Groceries | 0.4 mpd on a bill almost everyone has | UOB Preferred Visa |
Build your miles card stack
One card never covers everything. Put in what you actually spend and see which cards to hold together, and what to put on each.
Build my stack→The verdict, restated
A specialist that pays extremely well for one pattern of spending and close to nothing outside it. If you can honestly say you clear S$1,000 in one of these buckets every month, S$2,400 of bonus spend at this fee is hard to beat. If you cannot, the months you miss cost more than the months you hit are worth.
Sources
UOB Visa Signature Card T&Cs, checked 27 July 2026, and the UOB Visa Signature product page. Rates, fees and caps correct as of 5 August 2026. The second-year annual fee is aggregator-sourced at S$218 and was not confirmed on an official page. The petrol bonus excludes SPC and Shell, so drivers using those chains will earn less than the headline rate suggests. The annual fee being settled out of a UNI$ balance, and the roughly 13,000 miles that represents, is from my own experience rather than a figure UOB publishes: treat it as the shape of the problem, not an exact conversion, and check your own statement. This guide shares my own experience for education, it is not financial advice, and card terms change: always verify with the bank before applying.